

Rent-to-Own Ute Finance for Australian ABN Holders (Declined? We Can Help)
Need a ute for work but can’t access standard finance? Bloom helps Australian ABN holders obtain new and used work utes through rent-to-own and other alternative commercial finance options. We assess your current work, income, deposit and ability to repay, not only your credit history.
✓ Bad credit & defaults considered
✓ ABN holders – new or established
✓ Visa holders may apply
✓ No credit file impact to check eligibility
✓ Fast approvals
No credit check to enquire · No obligation


5-star rated on Google
600+ clients funded
FBAA member
Former Macquarie Bank specialists
Rent-to-Own Ute Finance
If you’ve been declined for ute finance due to bad credit, defaults, arrears, bankruptcy, court judgements or a low credit score, rent-to-own may still be an option.
At Bloom Financial Services, we help ABN holders access work ute finance where traditional banks and lenders may say no. Instead of focusing only on your credit file, we look at your current income, deposit, work situation and ability to make repayments.
This can suit tradies, subcontractors and small business owners who need a ute to keep working, but can’t get approved through standard ute finance.
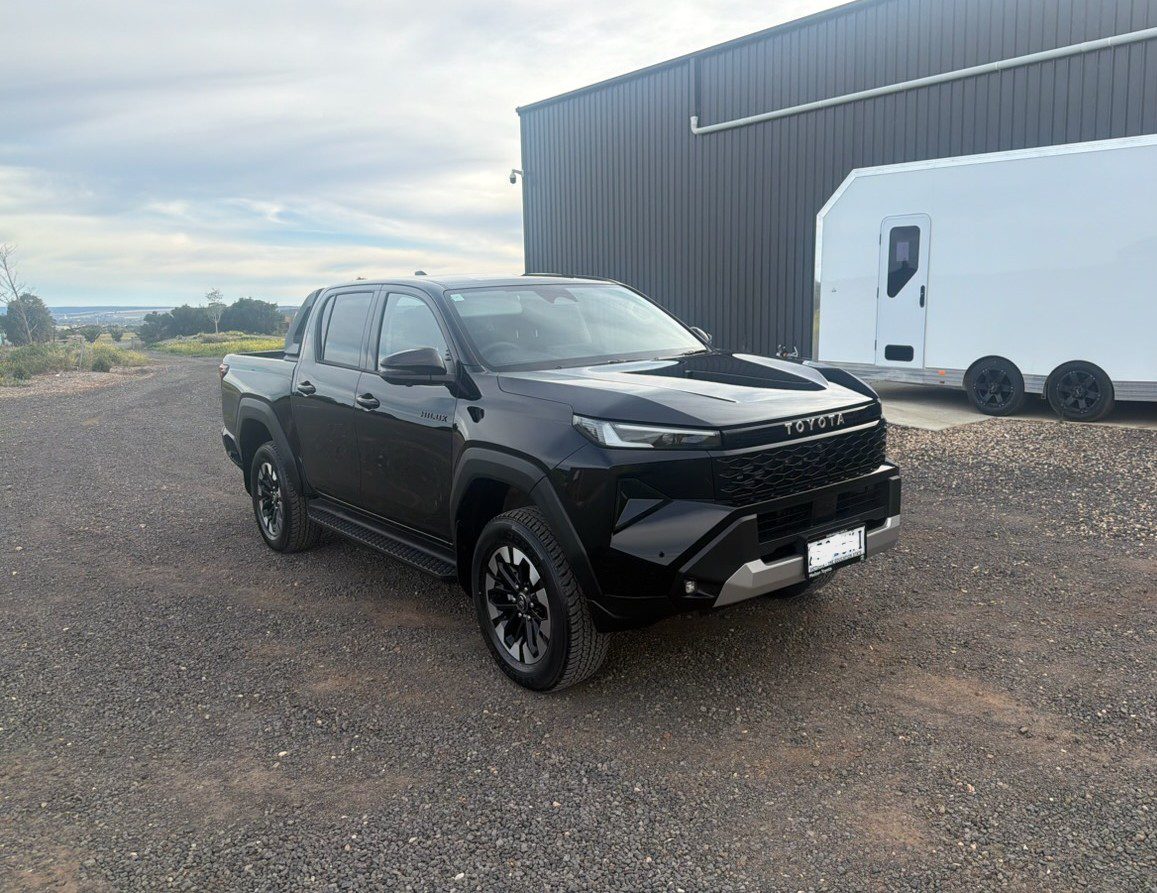
Outstanding finance defaults of $46k
funded!
A client had issues obtaining finance due to previous finance defaults caused by an ex-business partner. As this was an explanable and isolated incident with his new business doing well, we were able to provide a second chance at funding a vehicle via a rent-to-own product.

Previous vehicle repossession
funded!
A client came to us struggling to obtain finance for a replacement Ute after his was written off. The issue was he previously had a vehicle repossessed and another with bad repayment history. As his income situation had now improved, we were able to et him into a new ute via a rent to own product.

Finance default & new ABN
funded!
A client needed a ute for work as a heavy diesel mechanic – something suitable to carry tools and equipment to job sites. They couldn’t get mainstream finance due to an outstanding default, low credit score and new ABN. We were able to get them into a ute via a rent to own product
What Is Rent-to-Own Ute Finance?
Get a Work Ute – Even if the Banks Have Said No
Whether you’re a solo tradie, subcontractor, small business owner, or just starting out on your own ABN – our rent-to-own ute finance is designed to get you into a work-ready vehicle and back earning, without the hoops that traditional lenders put you through.
Unlike standard finance, rent-to-own doesn’t rely on your credit history or financials. It’s assessed on your current ability to make repayments – which means even if you’ve been knocked back before from banks or traditional lenders, there’s a strong chance we can still help.
At the end of the term, you can purchase the ute for a small final payment. If you’ve made your repayments on time, we may also be able to refinance the ute with a mainstream lender after around 12 months, potentially giving you a lower rate and repayment.
Quick Check – Do You Qualify?
✓ You hold an ABN – or you’re about to register one
✓ You have consistent income coming in, or a work contract lined up
✓ You have a deposit available, minimum is typically 20% or additional security (e.g. another vehicle you own outright)
✓ Dealer or private sales are ok.
If this sounds like you, there’s a strong chance we can help, even if you’ve been declined elsewhere. Call us on 0435 782 111 for a straight answer with no credit file impact.

How Rent-to-Own Ute Finance Works
Simple Steps from Application to Keys in Hand
We help you access rent-to-own ute solutions through our lender network – even where traditional finance isn’t available. Flexible, fast, and doesn’t rely on traditional bank or lending criteria.
1. Send us your contact details
Fill in the quick form on this page or call us on 0435 782 111. No paperwork yet – just your name, number and a brief outline of your situation.
2. We call to assess your situation
We ask about your work, income, deposit, and the type of ute you need. We give you an honest upfront answer – no credit check required to have this conversation.
3. We match you with the right option
We structure the deal through our lender network and present you with clear repayment figures before anything is signed. No surprises, no hidden fees.
4. Get into a ute and start earning
Once approved, you make structured weekly payments. At completion, ownership transfers to you – and we’ll look to refinance into mainstream lending after 12 months.
In many cases the ute pays for itself through the work income it generates from day one.
Who we lend to
Bad Credit Rent-to-Own Ute Finance – Who We Help
If a bank or broker has told you “no,” we’ll take a closer look.
Self-employed tradies & subcontractors
Plumbers, electricians, carpenters, concreting, landscaping – if you’re on the tools and need a ute to get to jobs, we understand your situation and can often structure an approval quickly.
Business owners with credit challenges
Bad credit, defaults, prior declines – we assess your current ability to earn and repay rather than focusing purely on your credit history. Past issues don’t automatically rule you out.
New ABNs with real work opportunities
Just registered your ABN? Banks want 2 years of financial if you’ve had any financial blemish – we don’t. If you’ve got work lined up and a deposit, we can often get you moving from day one.
Businesses looking to release equity
Using rent-to-own to free up working capital is a smart cashflow move for growing businesses. We can structure arrangements that preserve your liquidity while getting you the ute you need.
Visa holders & new arrivals
Various visas – including bridging visas can be considered. We’ve helped clients on 491, 482, 457, and bridging visas get into work vehicles that traditional banks wouldn’t touch.
Ex or Current Bankruptcy
Currently bankrupt or recently discharged? We assess your current situation, not just your history.
Rent-to-Own Versus Standard Ute Finance
Why Choose Rent-to-Own Over Standard Ute Finance?
Standard finance works well when you have strong credit and financials available. Rent-to-own is built for everyone else.
No major credit checks
No hard credit enquiries to check eligibility. We assess income potential, not just your credit history.
No full financials required
No need for full tax returns or BAS statements. Bank statements showing regular income are often sufficient.
Fast approvals
Most approvals within 24–48 hours. In some cases, same-day approval is possible so you can start work sooner.
Drive the ute you need now
Don’t wait months to sort your credit. Get into the ute, start earning, and build your financial position from there.
Own it at the end
This isn’t a lease with no end game. Ownership transfers to you at completion of the term for a small fee – it’s yours.
Rebuild your credit profile
Consistent payments create a positive repayment history with the provider, which may support a future refinance assessment. After 12 months we’ll often look to refinance into mainstream lending at better rates.
| Finance type | Credit check | Clean credit file | Good credit reference | Best for |
|---|---|---|---|---|
| Bank loan / chattel mortgage | Hard check | Yes | Yes in most cases | Strong credit, established ABN |
| Rent-to-own ✓ | Soft only in most cases | Not required | Not required | Bad credit, visa holders, declines |
Repayment guide
What Does Rent-to-Own Ute Finance Cost?
Rent-to-own repayments are higher than standard finance because you’re accessing credit without the usual requirements. Think of the difference as the cost of getting back on the road now rather than waiting. Here’s a general guide.
Repayment guide
What Does Rent-to-Own Ute Finance Cost?
| Ute value with 20% deposit | Weekly repayment (approx.) | Term |
| $25,000 | ~$250 – $300 / week | 1-4 years |
| $35,000 | ~$300 – $400 / week | 1-4 years |
| $50,000 | ~$450 – $600 / week | 1-4 years |
| $100,000 | ~$950 – $1,200 / week | 1-4 years |
Every deal varies depending on your deposit, the asset, and your credit profile. We’ll always walk you through exact figures before anything moves forward.
The stepping stone strategy
1. Now: Get approved through rent-to-own, start earning with the ute from day one
2. Months 1–12: Make every repayment on time, build clean financial records
3. Month 12: We review for refinance into mainstream lending at a lower rate
4. End of term: The ute is yours and you’re in a much stronger financial position
Client reviews
What Our Clients Say
Verified Google reviews from real clients we’ve helped across Australia.


Common questions
Frequently Asked Questions: Ute Finance with Bad Credit
Still have questions? Call us on 0435 782 111 – we’ll give you a straight answer.
In most cases, yes – but it varies. A deposit helps reduce risk and improves your chances of approval, especially if you have bad credit or previous declines. The exact amount depends on your situation, the ute, and your work. Usually lenders will require 20-30% or additional security such as another vehicle you own outright. If you’re unsure, we can assess your position and give you a clear answer upfront.
In most cases, yes. A deposit of 20–30% of the ute’s value is typically required. If you don’t have the full cash amount, a vehicle or asset you own outright can sometimes be used as additional security instead.
Yes. Many of our clients are newly self-employed or have just registered their ABN. You don’t need two years of financials — if you have work lined up and a deposit available, there’s a strong chance we can help.
Older and higher-kilometre utes may be considered, subject to their condition, value and suitability.
Yes — this is very common. Many of our clients are newly self-employed, subcontractors, or owner drivers just starting out. Even if you don’t have full financials yet, we can often work off your work history, contracts or income potential, particularly through rent-to-own options.
Yes – new and used utes are both accepted. Private sale purchases are also considered. There are no age limits on assets, which means older utes are also in scope where many lenders won’t go.
Most approvals are turned around within 24–48 hours of submitting a complete application. In some cases, same-day approval is possible. We’ll give you a realistic timeframe upfront based on your situation.
Yes – and we actively encourage it. After 12 months of consistent repayments, we’ll proactively review your position and look to refinance into mainstream lending at a lower rate, reducing your weekly repayments.
Yes, rent-to-own may be an option if you have been declined by banks or mainstream lenders.
Not always. If you have strong credit and full financials, a standard chattel mortgage will usually be cheaper. We’ll tell you honestly which option suits your situation – and we offer both. Rent-to-own is best for bad credit, prior declines, new ABNs, and clients who need to move quickly.
Related guides
Helpful Reading Before You Apply
Articles from our team covering the most common questions for ute finance applicants.
BAD CREDIT
How to get truck finance after bad credit in Australia
Practical steps to take now and how rent-to-own changes the equation for declined applicants.
VISA HOLDERS
Rent-to-own finance for temporary residents & visa holders
Which visa types are eligible and how we’ve structured approvals for clients in various visa situations.
HUB PAGE
Rent-to-Own Finance for All Assets – Trucks, Machinery & Vehicles
The full rent-to-own hub covering all asset types.
Looking for a van instead of a ute?
We also finance vans, light commercials, delivery vehicles & more on out rent to own page
Ready to get started?
Apply now and we’ll assess your options.
No obligation, no credit file impact to enquire. We’ll give you a straight honest answer on what’s possible – usually within 60 minutes.
☏ 0435 782 111
✉ info@bloomfs.com.au